Introduction
How home buying changed in 2026 is clear in one sentence: search, approval, tours, and closing moved online, while prices, monthly payments, and buyer age moved up. Buyers now start with AI search and digital preapproval, tour homes on video before visiting in person, and sign many closing documents from home, yet they face higher payments than buyers faced in 2020 and a market where older, equity-rich buyers hold a larger share.
Home buying in 2026 covers 5 linked changes: digital search and approval, video-first tours, remote closing, higher monthly costs, and an older buyer pool. The process still ends with the same legal steps: offer, inspection, appraisal, loan approval, and closing. The tools for each step changed more than the order of the steps.
- Search starts online: AI search and saved behavior now shape which listings a buyer sees first.
- Approval comes before touring: Digital preapproval sets a firm monthly payment limit before a buyer picks a home.
- Video tours filter, visits decide: A video tour rules homes out, but light, noise, and layout still need a physical visit.
- Many closings finish remotely: Remote online notarization covers many deals, but local and lender rules still decide each case.
- Costs decide more deals than style: Monthly payment, taxes, insurance, and upkeep set the real budget, not the asking price.
How Home Buying Changed Since 2020?
How home buying changed since 2020 is a shift from branch visits and paper files to phone-first search, digital documents, and video tours, with higher prices and higher monthly payments sitting on top of that faster process. In 2020, a buyer often drove to listings, met a lender in an office, and signed a stack of paper at a closing table. In 2026, a buyer often finds a home on a phone, uploads pay stubs and bank statements to a lender portal, and signs closing papers on a video call.
Three forces drove the shift. Lenders and title firms kept digital tools built for remote work. Buyers kept habits formed when in-person visits were hard to arrange. Higher rates after 2022 forced buyers to compare monthly payments with care, which pushed rate tools and digital preapproval to the front. Speed is now a buyer expectation, not a bonus. ServiceLink survey data reported in 2026 showed many buyers expect a fast close, while industry closing times still run longer in many cases (Source: ServiceLink, 2026).
For more home and daily life guides in this lane, browse the Lifestyle section for buying, moving, and home care topics that pair with a purchase plan.
Why Are First-Time Buyers Harder to Find in 2026?
First-time buyers are harder to find in 2026 because prices rose faster than starter incomes, monthly payments rose with rates, and older buyers with home equity kept buying while younger buyers waited. The National Association of Realtors (NAR) generational trends report released in April 2026 found that only 21% of buyers in its survey were first-time buyers, the lowest share since NAR began tracking the figure in 1981 (Source: NAR, 2026). The same report put baby boomers at 42% of buyers, millennials at 26%, Generation X at 25%, and Generation Z at 4%, with a median buyer age of 54 (Source: NAR, 2026).
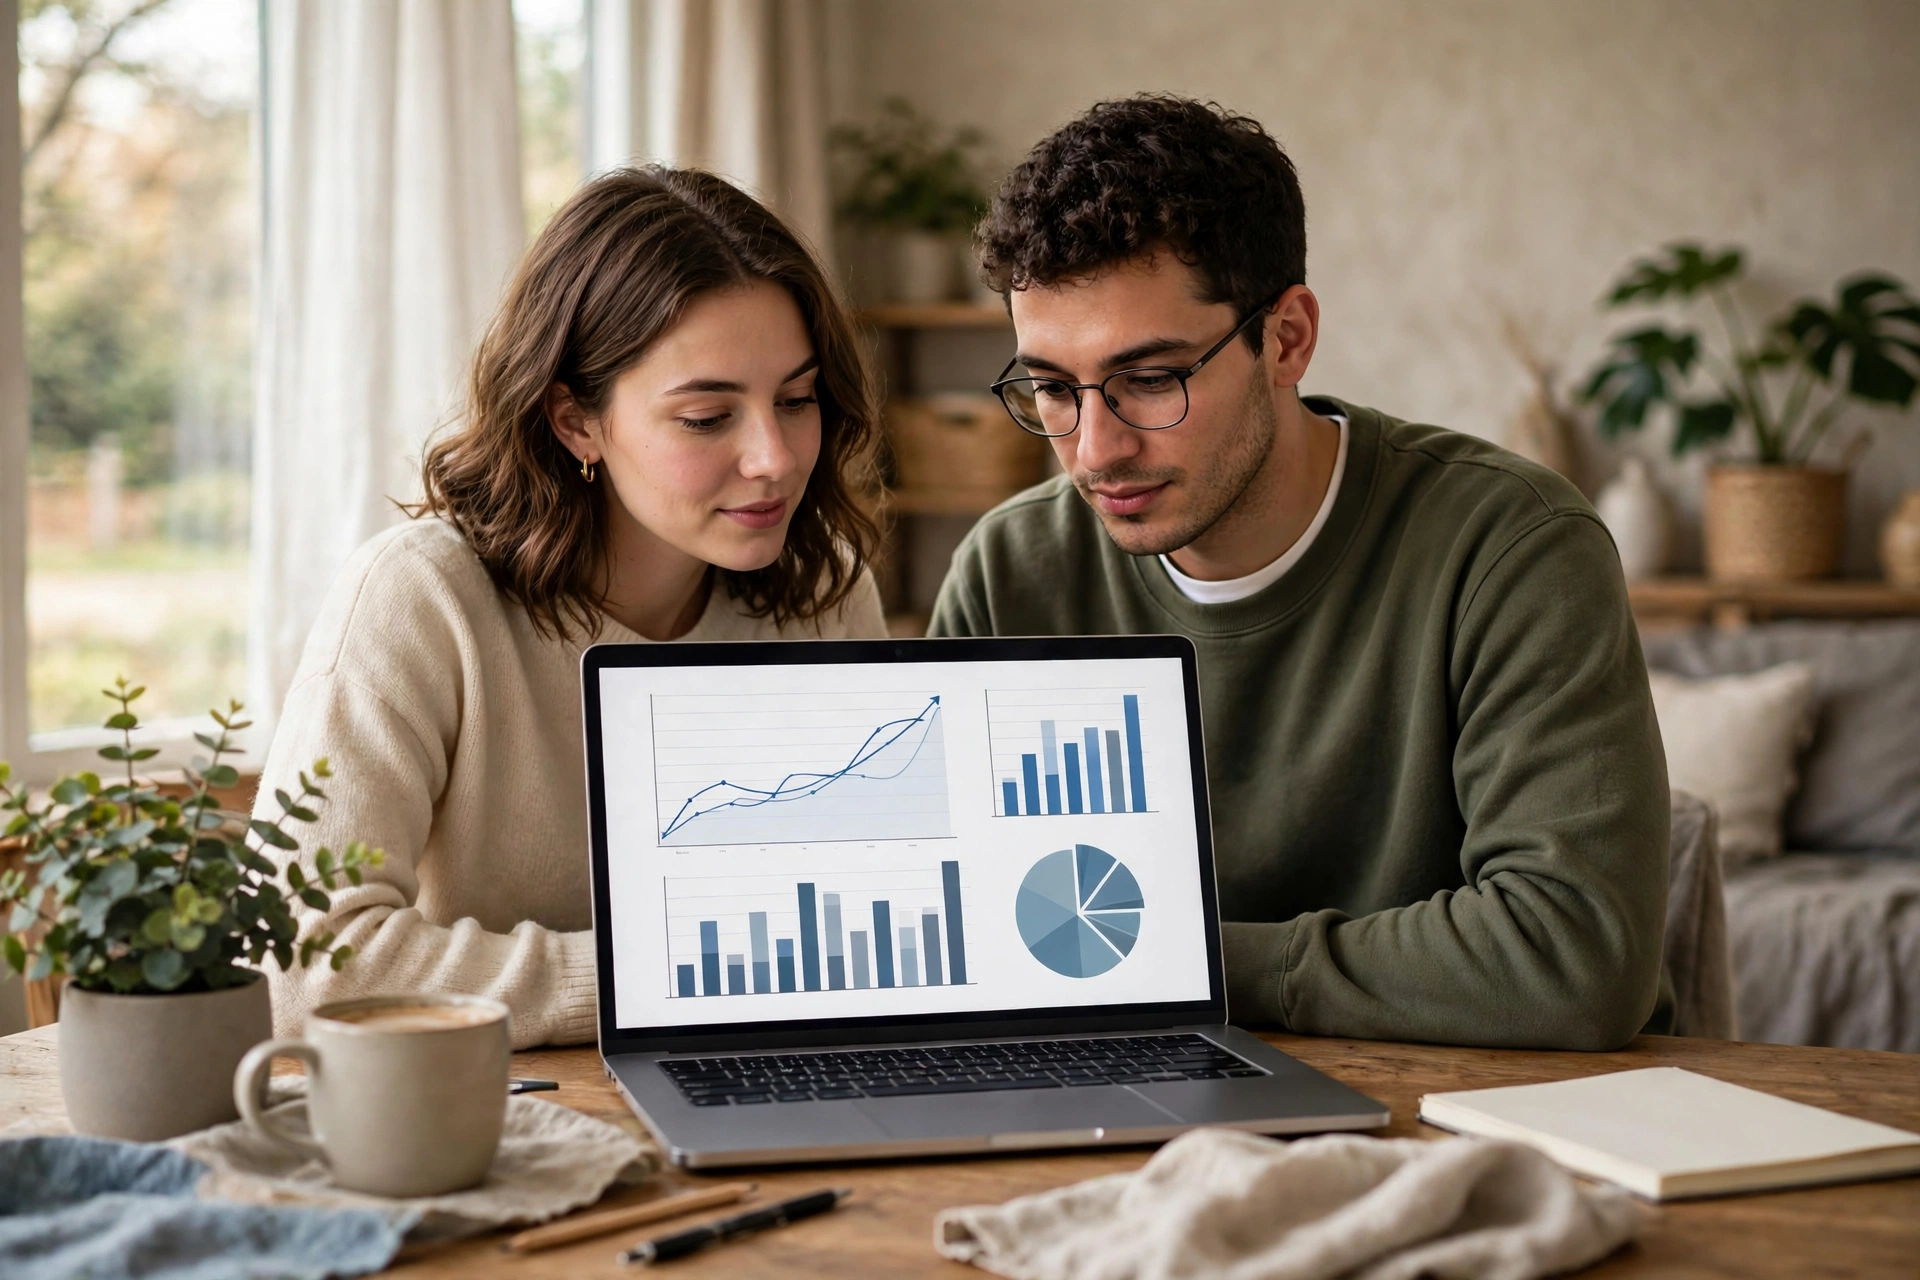
A second NAR figure looks different, and the difference matters. NAR monthly sales data for September 2026 put first-time buyers at 31% of sales that month, up from 30% in August 2026 and 30% a year earlier (Source: NAR, 2026). The generational report covers buyers who purchased between July 2024 and June 2025. The monthly figure covers one month of sales. The trend in both measures points the same way: entry got harder.
Price data backs the pressure. The median existing-home price in September 2026 was $417,500, up 1.3% from a year earlier, and NAR counted that month as the 39th straight month of year-over-year price gains (Source: NAR, 2026). NAR also reported a median single-family existing-home price of $432,900 in the third quarter of 2026, up 1.7% from a year earlier (Source: NAR, 2026).
How Do Mortgage Rates Shape What Buyers Can Afford?
Mortgage rates shape what buyers can afford by setting the monthly payment, and a small rate move changes that payment more than a small price cut changes it. A mortgage loan is a loan secured by real property, where the borrower pledges the home as security for the loan funds. The lender charges interest, and the borrower repays principal plus interest over a set term, often 30 years in the United States. A mortgage loan guide explains fixed-rate and adjustable-rate forms, down payment rules, and loan-to-value ratios in plain terms.
Rate levels in 2026 stayed high by 2020 standards, even when they eased from peaks. Freddie Mac data reported in October 2026 put the average 30-year fixed mortgage rate at 7.40% in the week covered by that report, the highest level since November 2023 in that reporting series (Source: Freddie Mac, 2026). ServiceLink data reported in 2026 put the average monthly mortgage payment near $2,057 and noted home prices up about 60% over the prior six years (Source: ServiceLink, 2026). NAR data for the third quarter of 2026 put the typical monthly payment at $2,251, with typical families spending 24.1% of income on mortgage payments (Source: NAR, 2026). Treat the three figures as a range, not as one exact payment, since they come from different samples and months.
A practical rule follows from those numbers. A buyer should lock a budget from the full monthly payment: principal, interest, property taxes, home insurance, and any homeowner association dues. A buyer should also test the budget at a rate 0.5% higher than the quoted rate. If the payment at the higher rate breaks the budget, the price range is too high.
What Does AI Home Search Change for Buyers?
AI home search changes home buying by turning a plain-language request into a matched list, so a buyer sees fewer off-target listings and spends less time filtering by beds, baths, and price alone. A buyer can type a request such as a three-bedroom home near good schools, 25 minutes from work, with room for a home office. AI search tools from Redfin, Realtor.com, and Homes.com, each launched or expanded in 2026, read listing text, location data, and past buyer behavior to return closer matches (Source: company announcements reported in 2026). The shared change is simple: search starts with intent, not with checkboxes.
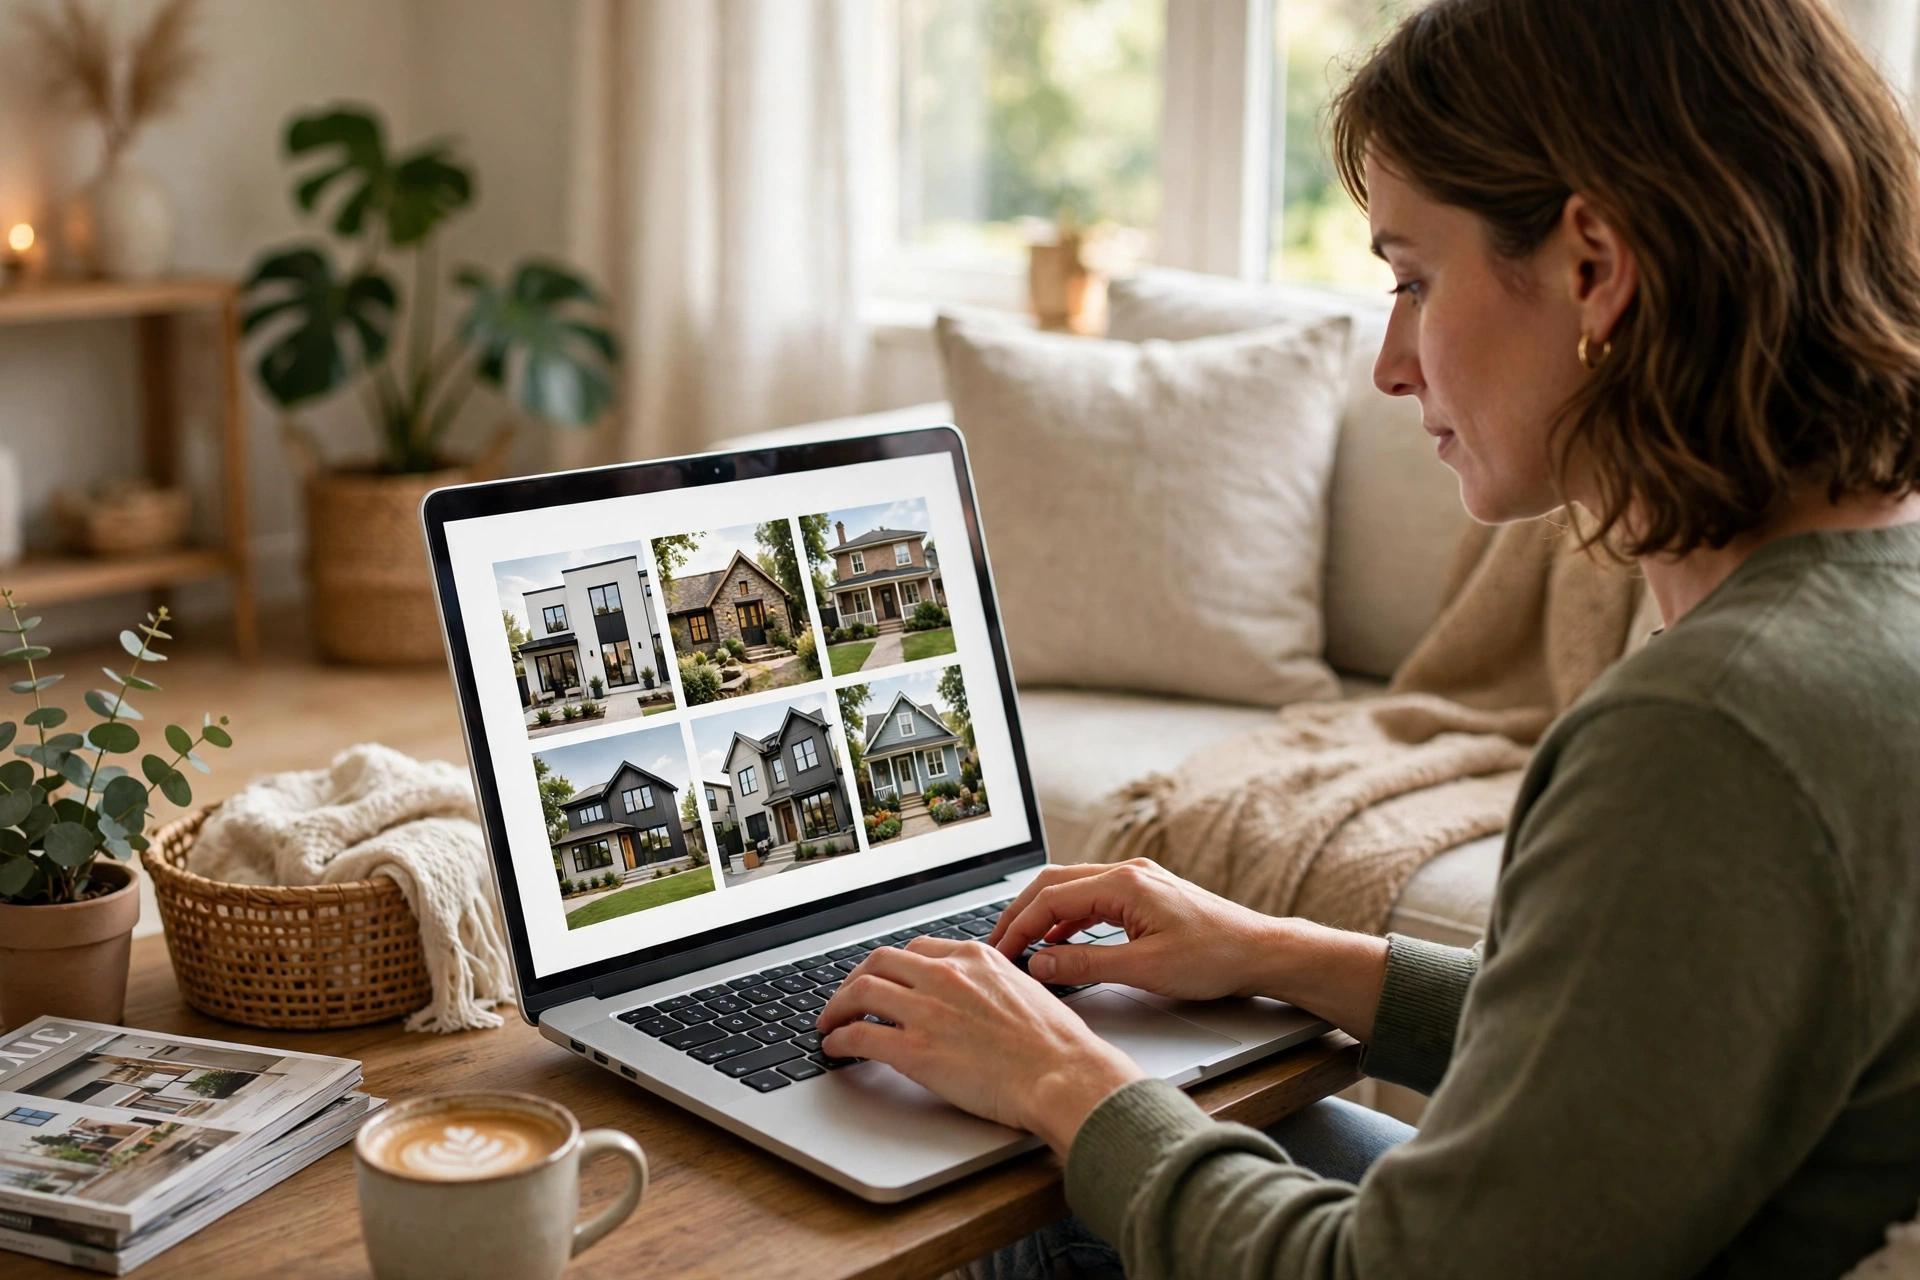
AI search has 4 clear limits. First, AI search only reads what a listing states, so a missing feature stays missing from the match. Second, AI search learns from clicks and saves, so casual browsing outside the budget can pull the feed off target. Third, AI search cannot judge light, noise, smell, or street feel. Fourth, AI search cannot verify price fairness. A buyer should use AI search to build a short list, then check each home with comps, disclosures, and a visit.
A first-hand observation helps here. In my own recent home searches for this guide, AI results improved fast once I saved only homes inside my price range and hid homes outside it. Casual saves for larger homes pulled the feed toward larger homes within two days.
How Do Virtual Tours and Remote Closings Work Now?
Virtual tours and remote closings work in 2026 as a filter plus a finish: a video tour rules homes out before a visit, and a remote closing finishes many deals without a closing table, subject to state law and lender approval. A 3D tour lets a buyer walk room by room on a phone, check layout flow, and spot deal breakers such as a tiny kitchen or a steep stair run. A live video tour lets a buyer ask an agent to open closets, run taps, and show street noise in real time. Neither tool replaces a physical visit, since cameras flatten depth and hide odors and night noise.
Remote online notarization, known as RON, lets a signer join a video call with a licensed remote notary, verify identity on camera, and sign documents with an electronic signature. Reports in 2026 put most states in the RON column for mortgage closings, with a small set of states still requiring in-person notarization for mortgages in some cases (Source: industry reporting, 2026). A buyer should confirm 3 items before counting on a remote close: the state where the property sits allows RON for that loan type, the lender accepts RON for that loan, and the title firm can run the RON session. If any of the 3 answers is no, the buyer needs an in-person signing or a mobile notary visit.
Old Process Versus 2026 Process
The old process versus the 2026 process differs in tools at each step, while the legal checks stay the same. The table below lays out the change in one view.
| Step | Old process, around 2020 | 2026 process |
|---|---|---|
| Search | Drive to listings, paper printouts, agent phone calls | AI search, saved alerts, phone-first listings |
| Preapproval | Branch visit, paper pay stubs, slow reply | Portal upload, fast digital preapproval, payment range set early |
| Tours | In-person only, many wasted visits | Video and 3D tours first, in-person visits for finalists |
| Offer | Paper offer, slow back and forth | Digital offer, e-signature, faster counteroffers |
| Inspection and appraisal | Paper reports, long waits for copies | Digital reports, photos, and portals, same physical checks |
| Closing | Closing table, paper stack, in-person notary | Remote online notarization for many deals, e-signatures, same legal review |
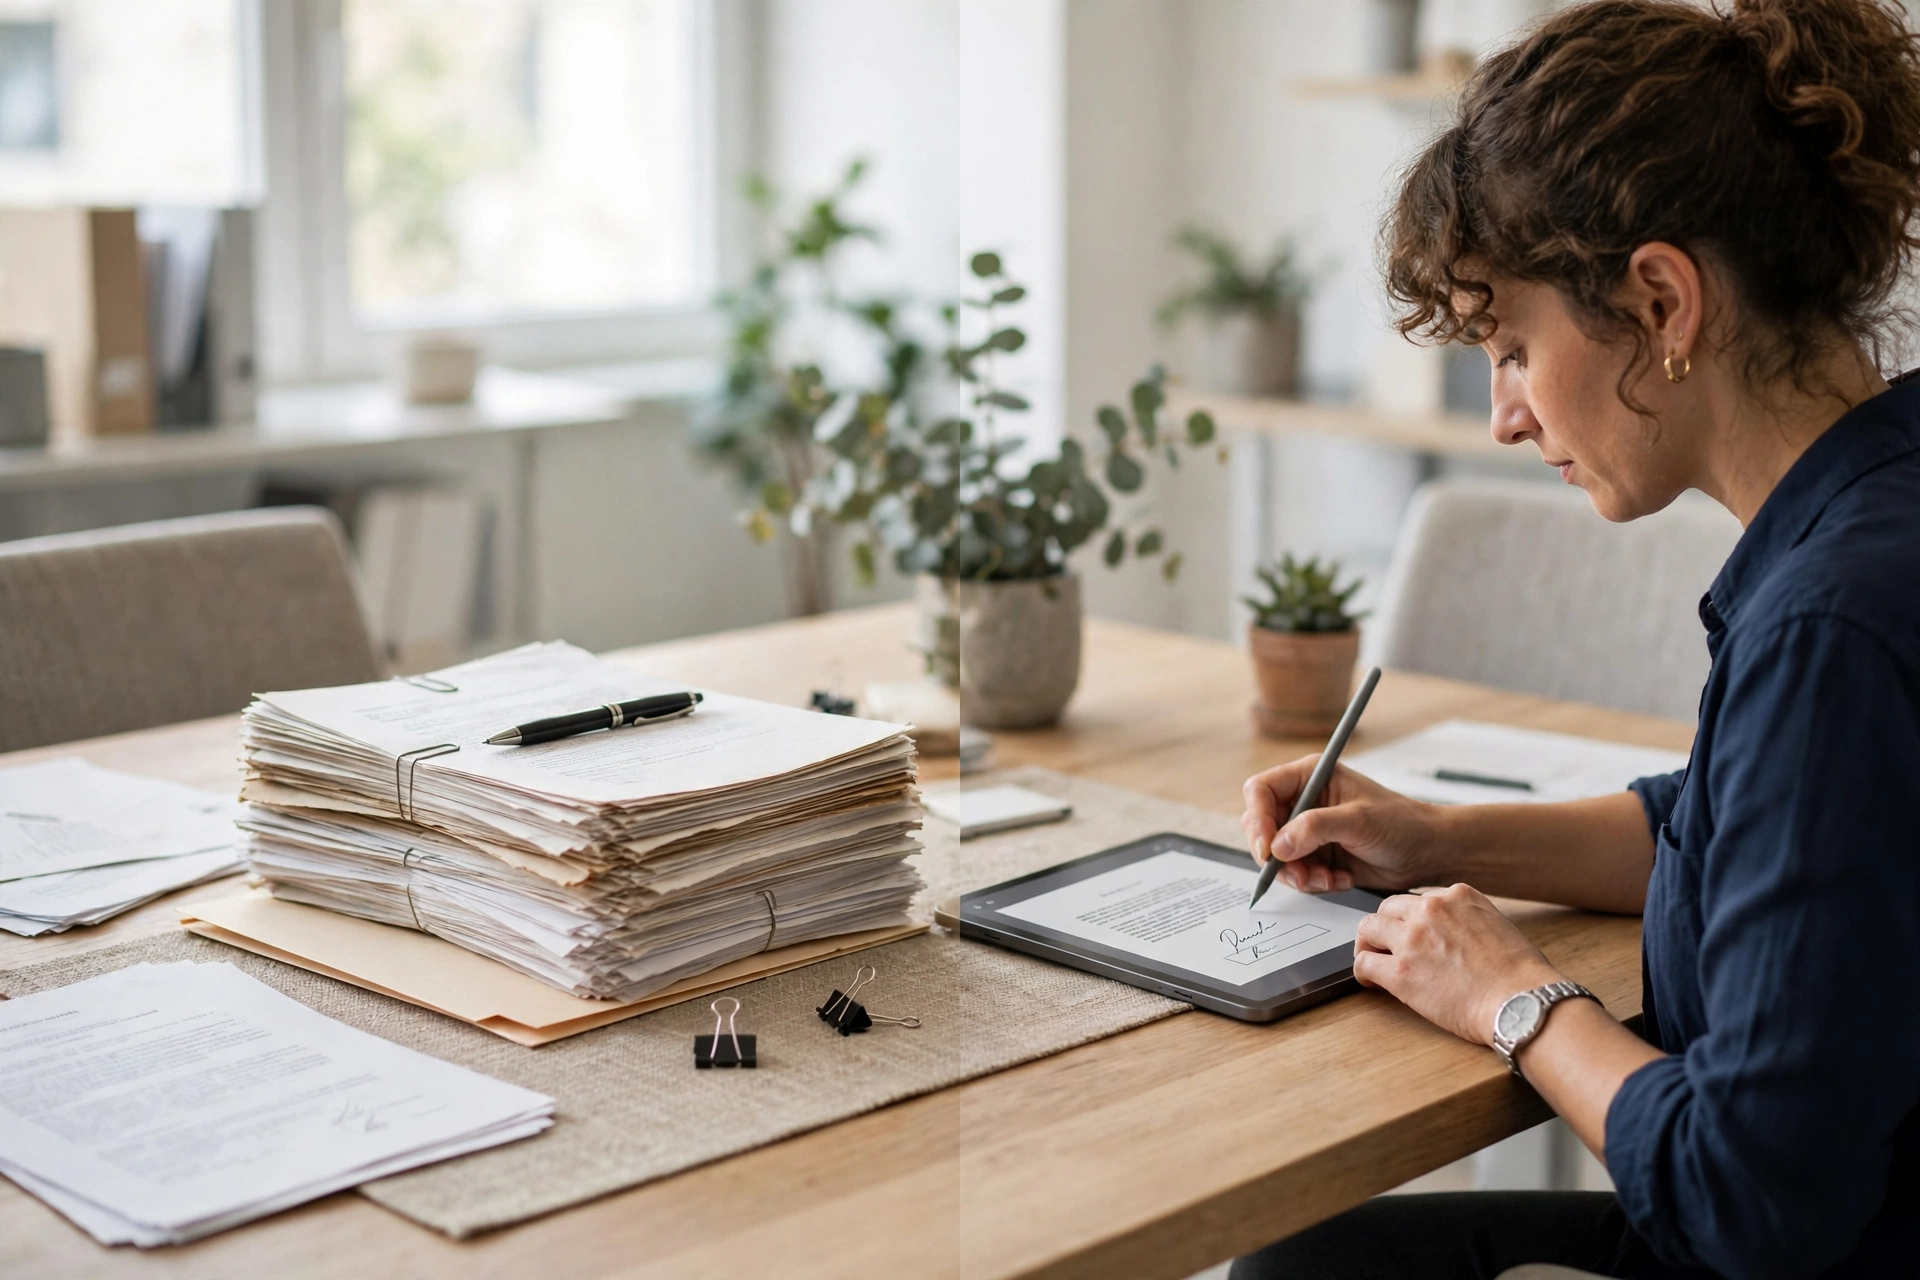
Faster tools do not remove risk. Inspection still needs a licensed inspector on site. Appraisal still needs a value opinion tied to recent sales. Loan approval still needs income, employment, and credit checks.
How Do You Buy a Home in 2026, Step by Step?
You buy a home in 2026 by setting a payment budget first, then searching, touring, offering, inspecting, and closing in that order, with digital tools handling the paperwork at each step. The steps below keep the order tight and the checks visible.
- Set the full monthly payment limit, with taxes, insurance, and dues included.
- Get digital preapproval and confirm the rate lock window in writing.
- Build a short list with AI search, then filter by price, commute, and school zone.
- Run video tours for the full short list and visit only the finalists in person.
- Check recent comparable sales for each finalist before setting an offer price.
- Make the offer with inspection and appraisal terms stated in writing.
- Order the inspection, read the full report, and price repairs before waiving any term.
- Track appraisal, loan conditions, and title work in the lender portal each week.
- Confirm RON eligibility or book an in-person signing well before closing day.
- Do a final walkthrough, confirm funds, sign, and record the deed.
Payment first, home second, offer third. That order held in 2020, and it holds in 2026.
What Should Buyers Check Before Making an Offer?
Buyers should check 5 items before making an offer in 2026: the full monthly payment, comparable sales, inspection scope, appraisal risk, and closing costs. The full monthly payment check uses the lender estimate, not a portal estimate. The comparable sales check uses closed sales from the past 3 to 6 months in the same area, not asking prices for unsold homes. The inspection scope check names roof, foundation, plumbing, electrical, heating, and cooling, plus flood zone or sewer risk. The appraisal risk check asks who covers the gap if the appraisal comes in below the offer price. The closing cost check asks for a written estimate of lender fees, title fees, prepaid taxes, and insurance.
Inventory data gives buyers more room to run those checks. NAR reported September 2026 inventory at 1.6 million units, the highest level since November 2019 in that series, equal to 4.8 months of supply at the September sales pace (Source: NAR, 2026). More choice means less pressure to waive inspection or appraisal terms on the first home seen.
After closing, plan the move with How to Plan a Stress-Free Move.
Which Homes and Locations Fit Remote Work and Family Life?
Homes and locations fit remote work and family life in 2026 when the home gives work a closed door, the location keeps daily trips short, and the price leaves room for upkeep. Remote work changed location math for many buyers. A buyer who works from home 3 days a week can live farther from an office than a daily commuter, but the buyer still needs reliable internet, a quiet work room, and a workable office-day commute.
A location check has 4 parts. First, test internet speed at the address and confirm provider options, since a home office fails on a weak connection. Second, drive the commute at rush hour on a workday, since map times at noon mislead. Third, walk the street at night and on a weekend, since noise and parking change by hour. Fourth, check resale factors that outlast one job: school quality, flood risk, and upkeep costs for roof, heating, and cooling systems.
Conclusion
How home buying changed in 2026 comes down to faster tools, higher costs, and an older buyer pool, with the same core checks deciding a good purchase. Digital search, video tours, and remote closing save time. Higher prices and higher monthly payments demand a payment-first budget. Older buyers with equity set much of the competition, while first-time buyers need more time and sharper checks to enter. A buyer who sets a payment limit, tours on video first, checks comps and inspection scope, and confirms remote closing eligibility buys with the new tools and the old discipline at once. Voice of Wave covers home and daily life topics with that same check-first approach.
Explore more home guides: Browse the latest articles on the Voice of Wave blog for more home buying, moving, and home care guides.
Frequently Asked Questions
How has home buying changed in 2026?
How home buying changed in 2026 is a move to phone-first search, digital preapproval, video tours, and remote closing, with higher prices and higher monthly payments than in 2020. Buyers now filter homes on video before visiting, sign many closing documents online, and compare monthly payments with care. The legal steps of offer, inspection, appraisal, and closing remain the same.
Are first-time buyers really at a record low?
No, not in every measure, but the long-run generational measure hit a record low in 2026. NAR generational data put first-time buyers at 21% of buyers surveyed, the lowest share since 1981 (Source: NAR, 2026). NAR monthly data for September 2026 put first-time buyers at 31% of sales that month (Source: NAR, 2026). The figures cover different periods.
Can I close on a house fully online in 2026?
Yes, in many cases, but not in every state or for every loan. Remote online notarization lets a buyer sign on a video call with a licensed remote notary in many states. A buyer should confirm state law, lender acceptance, and title firm capacity before closing day. If any check fails, an in-person signing or mobile notary visit is needed.
How much house can I afford in 2026?
You can afford the home whose full monthly payment, with taxes and insurance, fits your budget, not the home with the highest lender quote. Start from take-home pay, subtract fixed costs and savings, and set a payment limit from the remainder. Test the payment at a rate 0.5% higher than quoted. If it breaks the budget, lower the price range.
Does AI home search replace a real estate agent?
No, AI home search narrows the list, while an agent checks price, terms, disclosures, and closing details. AI tools match listings to stated preferences and past behavior, but AI tools cannot verify listing accuracy, judge a street at night, or negotiate repair credits. Use AI search for options, then use an agent, inspector, and lender for verification and terms.
Should I waive inspection to win a bidding war?
No, waiving inspection trades a short-term win for unknown repair costs after closing. Inspection reports cover roof, foundation, plumbing, electrical, heating, and cooling, and repair prices can run far above the amount saved by winning fast. With more inventory, a buyer can often keep inspection terms and still compete with a clean offer and a fast timeline.