Written by Sarah Mitchell for Voice of Wave.
Last updated: October 2026
Introduction
Wills and trusts are the two main legal tools that control who receives your property, who manages your affairs, and who cares for your minor children after death or incapacity. A will acts after death through probate court. A funded trust can act during life and after death outside probate.
This Voice of Wave guide explains wills and trusts in plain language, compares probate, privacy, cost, and control, and gives steps for a plan that fits a family, a business, or property in more than one state. A will names an executor and guardians. A trust names a trustee and sets distribution rules. Together, wills and trusts cover death, incapacity, guardianship, staged gifts, and the practical checks that keep a plan working.
Key Takeaways
- Wills and trusts serve different jobs: a will acts after death through probate, while a funded trust can act during life and after death outside probate.
- Only a will names guardians for minor children, so a trust alone does not finish a family plan.
- A trust controls only assets transferred into the trust, so funding is a required step, not an optional extra.
- Beneficiary designations on retirement accounts and life insurance usually override a will, so every form must match the plan.
- Review wills and trusts after marriage, divorce, a birth, a death, a move, a business change, or a large change in assets.
Table of Contents
- What Are Wills and Trusts?
- How Does a Will Work After Death?
- How Does a Trust Work During Life and After Death?
- Will vs Trust: What Is the Difference?
- Which Option Fits Your Situation?
- What Types of Trusts Should You Know?
- How Do You Create Wills and Trusts?
- What Mistakes Leave a Plan Unfinished?
- How Much Do Wills and Trusts Cost?
- When Should You Review Wills and Trusts?
- Frequently Asked Questions
- Conclusion
What Are Wills and Trusts?
Wills and trusts are legal documents that direct property transfer, name managers for an estate, and set rules for beneficiaries. A will states who receives probate property after death, names an executor, and names guardians for minor children. A trust is an arrangement in which a settlor transfers property to a trustee, who holds it for beneficiaries.
A will covers only probate property, which means property owned in the sole name of the person who died, without a beneficiary form or joint title. A trust covers only trust property, titled in the trust name or payable to the trust. Property with a beneficiary form, such as a retirement account, passes under that form and not under the will. Every asset must be sorted into one path: will, trust, beneficiary form, or joint title.
Readers who want the business side of asset lists can explore the Business category for guides on money, records, and small business topics.
How Does a Will Work After Death?
A will works after death when a probate court admits the will, appoints the executor, and supervises payment of debts, taxes, and distribution. The executor files the will, gathers probate assets, pays valid debts and taxes, and distributes the rest under the will terms. Probate is public, so key filings become court records.
A will must meet state signing rules, usually a signed document plus witnesses who are not beneficiaries. Some states accept a handwritten will, while other states do not. A will can also create a testamentary trust, which starts only after death and passes through probate first. The history and formal rules for a will and testament cover signing, witnesses, and revocation. A will alone does not cover incapacity, so a power of attorney and a health care directive are still needed.
How Does a Trust Work During Life and After Death?
A trust works during life when the settlor transfers assets into the trust, and the trustee manages those assets during life, incapacity, and after death. In a revocable living trust, the settlor often serves as first trustee, keeps control during life, and names a successor trustee for incapacity or death. Distribution can happen at once, in stages, or on set conditions.
A revocable living trust usually becomes irrevocable at the settlor’s death, so the successor trustee follows the written terms. The legal rules for trusts explain the settlor, trustee, and beneficiary roles and fiduciary duties. A trust does not cover assets left outside it, so a pour-over will is still needed, and stray assets still pass through probate first. A trust also does not name guardians.
Will vs Trust: What Is the Difference?
The difference between a will and a trust is timing, court control, privacy, incapacity cover, and control over distribution timing. A will acts only after death and needs probate. A funded trust can act during life and after death, stays private, and can stage gifts over years.
| Feature | Will | Trust |
|---|---|---|
| When it takes effect | After death only | During life for a living trust, and after death |
| Probate for covered assets | Yes, probate is required | No, for assets held in the trust |
| Privacy | Public court record | Private administration |
| Incapacity cover | No, executor authority starts after death | Yes, successor trustee can act during incapacity |
| Names guardians for minor children | Yes | No, a will is still needed |
| Cost to create | Usually lower | Usually higher |
| Ongoing work | Low, mostly review and storage | Higher, funding and record checks are required |
| Control over distribution timing | Limited, mostly at once after probate | High, staged or conditional gifts are possible |
| Property in more than one state | Probate may be needed in each state | One trust can hold property in more than one state |
The table shows why many plans use both tools: the will covers guardianship and stray assets, while the trust covers incapacity, privacy, and staged gifts. A plan with only a will leaves incapacity and probate delay unsolved. A plan with only a trust leaves guardianship and stray assets unsolved. The right mix depends on family facts, asset titles, and state probate rules, not on a general claim that one tool fits every family.
Which Option Fits Your Situation?
The option that fits your situation is the option that matches your family facts, asset titles, probate costs in your state, and need for incapacity cover. A simple will often fits a small, single-state estate with no minor children. A revocable living trust often fits parents, business owners, blended families, and owners of property in more than one state.
Ask these 5 questions before choosing:
- Do you have minor children who need a guardian named in a will?
- Do you own real estate in more than one state?
- Do you want a successor trustee to manage assets during incapacity?
- Do you want gifts to children paid in stages rather than at once?
- Do you want estate details kept private rather than filed in probate court?
A “yes” to question 1 means a will is required. A “yes” to questions 2, 3, 4, or 5 points toward a trust in addition to the will. A “no” to all 5 questions points toward a simple will plus powers of attorney and beneficiary checks. State probate rules change the math, so a local estate planning attorney can confirm probate fees and signing rules for the state where property sits. A check that catches errors is to read the beneficiary list on each account next to the will, line by line, and fix any mismatch before signing.
What Types of Trusts Should You Know?
The trust types to know are revocable living trusts, irrevocable trusts, testamentary trusts, special needs trusts, and charitable trusts. A revocable living trust is created during life, can be changed during the settlor’s life, and avoids probate for funded assets. An irrevocable trust cannot be changed freely, and the settlor gives up control.
Two more forms matter for families. A QTIP trust, which stands for Qualified Terminable Interest Property trust, gives income to a surviving spouse for life, then sends the rest to other beneficiaries, often children from an earlier marriage. A spendthrift trust limits a beneficiary’s access to principal and protects trust assets from that beneficiary’s creditors. A trust for a minor child can hold gifts until a set age.
Read The Accounting Equation Explained to see how business assets are tracked.
How Do You Create Wills and Trusts?
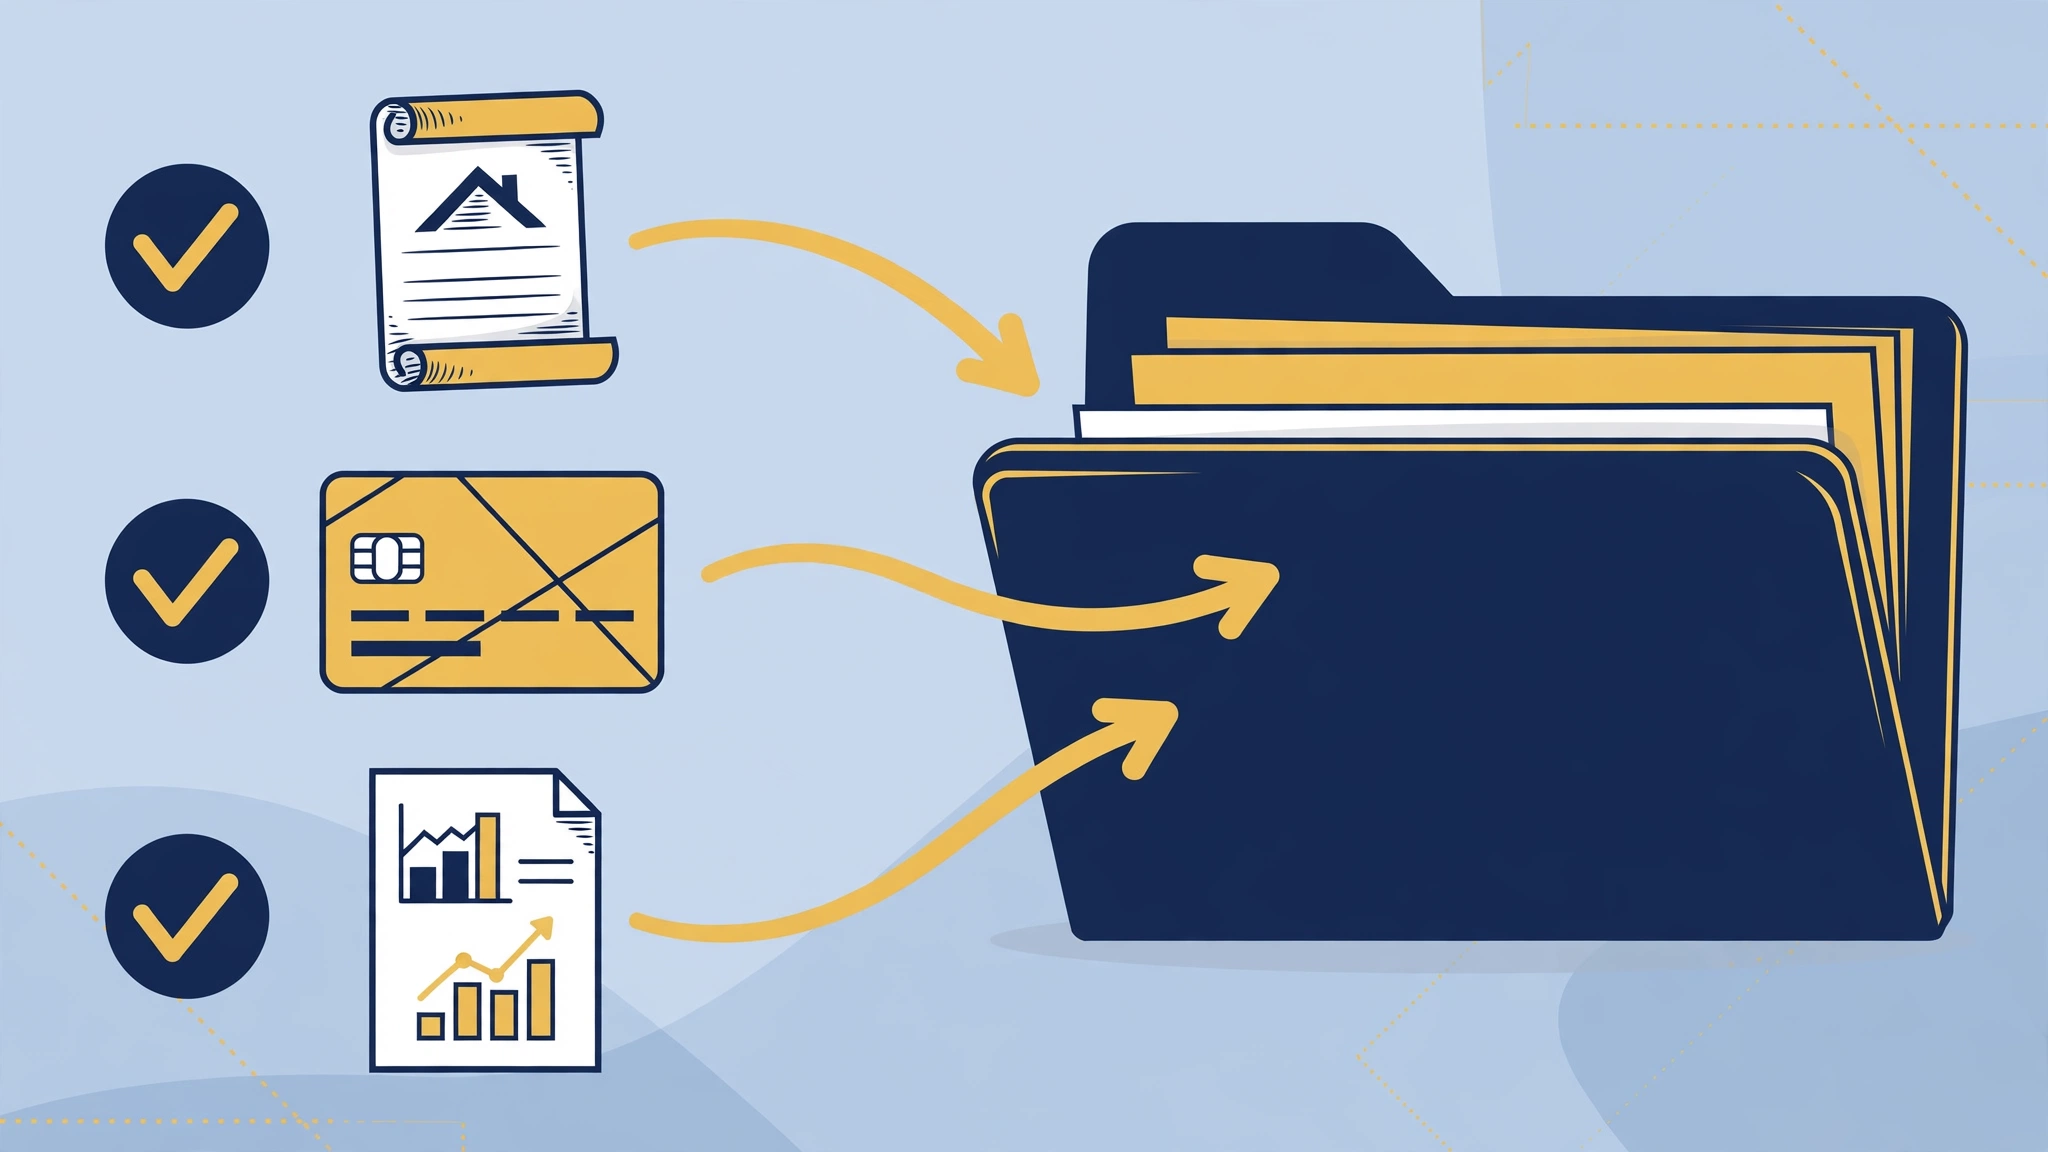
To create wills and trusts, list assets and titles, choose people for each role, draft documents under state rules, sign with required witnesses, fund the trust, and store signed originals where helpers can find them.
- List every asset with its title, owner, and beneficiary form.
- List every debt, so the plan covers payment from estate or trust funds.
- Choose beneficiaries and the share or asset each beneficiary receives.
- Choose an executor and a backup executor for the will.
- Choose a trustee, a successor trustee, and a backup for the trust.
- Name guardians and backup guardians for minor children in the will.
- Draft the will, the trust, powers of attorney, and health care directives.
- Sign each document under state rules, with witnesses and notarization where required.
- Fund the trust by retitling accounts, recording deeds, and updating beneficiary forms.
- Store signed originals in a safe place and tell executors and trustees where the originals sit.
- Give copies or access details to the executor, trustee, guardians, and attorney.
Funding needs care per asset type. Real estate moves by a recorded deed into the trust name. Bank and investment accounts move by retitling, or by a payable-on-death or transfer-on-death form where that form fits the plan. Business interests move under business documents, which may need owner consent. Retirement accounts usually stay in the owner’s name, with the trust, spouse, or person named on the beneficiary form.
What Mistakes Leave a Plan Unfinished?
The mistakes that leave a plan unfinished are an unfunded trust, mismatched beneficiary forms, missing guardians, lost originals, and a plan never reviewed after life changes. An unfunded trust is the most common mistake: the deed and accounts stay in the owner’s name, so those assets still pass through probate. A mismatched form is the second common mistake: a retirement account still names a former spouse, and that form overrides the will.
Four more mistakes cause delay. A will signed without required witnesses can fail in court. A plan with only one executor, trustee, or guardian leaves no backup. A plan that hides passwords and account lists forces helpers to search for assets during grief. Each mistake is fixable before death with funding, beneficiary, signing, and storage checks.
How Much Do Wills and Trusts Cost?
Wills and trusts cost more to create for a trust than for a will, but a will can cost more after death through probate fees, court costs, and delay. A trust plan needs a trust document, a pour-over will, powers of attorney, and funding work. Attorney fees vary by state and complexity, so a written quote from 2 or 3 local attorneys gives the real range.
Probate costs also vary by state and estate size, and can include court filing fees, executor fees, attorney fees, appraisal fees, and bond costs. A trust avoids probate fees for funded assets, but still needs trustee work and tax filings after death. Count both sides: creation cost plus administration cost. Ask each attorney for the drafting fee, the funding help fee, and the expected administration cost.
When Should You Review Wills and Trusts?
You should review wills and trusts after every major life event and on a regular cycle, even when no life event has happened. Marriage, divorce, a birth, a death, a move to a new state, a home sale, a business sale, and a large change in wealth each change the facts the plan was built on. State signing and probate rules differ, so a move can require updates.
A regular review catches slow changes. Check beneficiary forms, trust funding, executor and trustee choices, and storage during each review, because new accounts often start outside the trust and people age or move.
In Caring.com’s 2025 wills survey, 24% of United States adults said they have a will and 13% said they have a living trust, down from 33% with a will in 2022 (Source: Caring.com, 2025). In the same survey, 43% of respondents without a will said they just had not gotten around to making one (Source: Caring.com, 2025). A review date turns a one-time signing into a plan that still matches family facts.
Conclusion
Wills and trusts work best as a pair: a will names guardians and catches stray assets, while a funded trust manages assets during incapacity and passes trust assets outside probate. Choose the mix of will, trust, powers of attorney, beneficiary forms, and joint titles that matches your family facts, asset titles, and state rules. List assets, choose people with backups, sign under state rules, fund the trust, align beneficiary forms, and store originals where helpers can find them.
For more business and money guidance from Voice of Wave, keep the plan simple, written, funded, and reviewed, and the family will face clear instructions instead of court delay and guesswork.
Browse the latest Voice of Wave articles for more business and money guides: https://www.voiceofwave.com/blog/
Frequently Asked Questions
Do I need a will or a trust?
You need a will if you have minor children, property in your sole name, or wishes that probate must follow. You need a trust in addition to a will if you want incapacity cover, privacy, staged gifts, or probate avoidance for funded assets. Most families need both tools.
Can a trust replace a will completely?
No, a trust cannot replace a will completely. Only a will names guardians for minor children, and only a pour-over will sends stray assets into the trust at death. A trust alone leaves guardianship and unfunded assets uncovered, so a will is still required.
What happens if I die without a will?
If you die without a will, state intestacy law decides who receives your probate assets, and a court appoints an administrator. The result may not match your wishes, and the process can take longer and cost more than probate with a valid will in place.
Does a living trust avoid probate for all my assets?
No, a living trust avoids probate only for assets held in the trust. Assets left in your sole name, without a beneficiary form, still pass through probate, even when a pour-over will later sends them into the trust after probate closes.
Who should I choose as executor or trustee?
Choose a person who is organized, honest, and willing to serve, and name a backup for each role. An executor works under court supervision, while a successor trustee works outside probate for trust assets, so each role needs a person suited to that job.
How often should I update my will and trust?
Update your will and trust after marriage, divorce, a birth, a death, a move, or a large change in assets. Review beneficiary forms and trust funding during each review, so new accounts and new property do not sit outside the plan.
Do beneficiary designations override my will?
Yes, beneficiary designations on retirement accounts and life insurance usually override a will. Check every form against the will and trust plan, and update any form that still names a former spouse, a deceased person, or the wrong share.